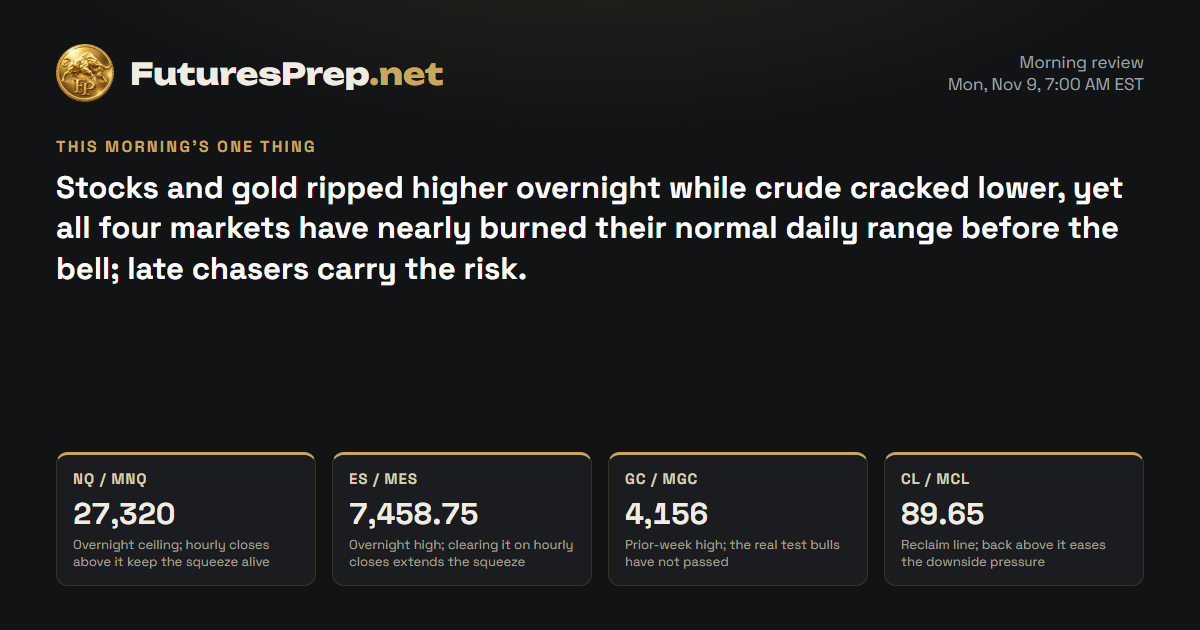
The Lines in the Sand
The Trap
After a hard rebound that has already covered most of a normal day's travel, latecomers tend to pile in near the overnight high just as the move runs out of room. On the other side, shorts who leaned on Friday's weakness got squeezed when the gap filled.
The Read
Bears own the week, but Friday's chip-led rebound off 26367.25 left late shorts offside. Price clawed back to 27107.25, then stalled under the 27425 session high and the daily average up at 29020.6. That squeeze is the strongest argument against the bears, and it still has not repaired the break below 28232.25. The tape went quiet into the close, coiled under resistance between 27250 and 27425. Hold above 27300 and the door opens; lose 27055 and the 26367.25 floor comes back into play.
Morning review · Nov 9, 7:30 AM EST
Bears pushed MNQ down to 26737.25 overnight, then lost their grip as bulls ripped it back through the session open and filled the gap to Friday's 27107.25 close. Price now sits at 27199.75, but it is still far below the daily average at 29020.6 and trapped inside last week's range. This is a rebound, not a proven turn, and most of the day's normal range is already spent. Hourly closes above 27320 open the door toward 27425; lose 27030 and the 26810-26737.25 pocket comes back into play.
Overnight evidence · 13 cited findings
Overnight price action
- MNQ traded from an overnight low of 26737.25 to a high of 27320 and stood at 27199.75 at the cutoff.
- The 228-point down gap to 27107.25 filled during the overnight session.
- Price recovered from the 02:00 selloff and produced higher closes through 06:00, finishing above H1 EMA21 at 27130.69.
- The overnight range was 582.75 points, equal to 0.891 ADR.
Overnight events
- No verified high-impact scheduled release occurred inside the overnight observation window.
- The next verified major release is Nov. 10 CPI at 08:30 ET.
- Exact Nov. 9 Treasury auction terms were not conclusively extracted from the primary announcement page.
- No live yield, dollar or options-market observations were available to confirm the macro transmission.
What changed
- Price action invalidates the prior bearish direction and establishes a bullish morning rebound.
- Gap completion and the H1 EMA21 reclaim support the change.
- High ADR consumption and resistance at 27320-27425 limit confidence.
- The rates-sensitive employment backdrop opposes the bullish price signal.
- Net result: bullish morning direction, INVALIDATED last night's read and unchanged weekly bearish weekly view.
Index drivers
On Friday, NVDA and TSLA led the heavyweights higher, with META, AVGO and GOOGL also gaining. MSFT, AAPL and AMZN slipped, so leadership was split. NVDA is scheduled to report after the close on Nov. 17.
Market data as of Nov 9, 7:33 AM EST · Weights as of 2026-09-30
Evidence · 13 cited findings
Price action · weekly / daily / H1
- W45 closed bearish at 27107.25 after opening 28587, taking the prior-week low at 28232.25 and accepting below it; the weekly low was 26367.25.
- Friday rebounded from 26367.25 to a bullish daily close, but the 27107.25 settlement remained below the 27425 session high, the broken 28232.25 shelf and daily EMA21 at 29020.6.
- The Nov. 5 09:00-10:00 ET decline of roughly 850 points established the structural break; the subsequent recovery has not repaired it.
- Friday's last completed H1 closed 27107.25 below its approximately 27181.5 EMA21, while 27250-27425 is the nearest resistance zone.
- The bearish scenario requires an H1 close below 27055; a Sunday reopen above 27300 would invalidate the immediate bearish lean.
Metrics
- Friday used 1.617 ADR and traded at 1.407 times its 30-session average volume, confirming unusually large participation but also increasing mean-reversion risk.
- The daily close was 2.925 ADR below EMA21, supporting the higher-timeframe downtrend rather than a confirmed reversal.
- The final H1 range was 71.75 points versus a 105-point expansion threshold, so the market ended compressed rather than actively expanding.
Sentiment & current events
- October payrolls rose 165,000, unemployment was 4.1% and earnings rose 0.4% month over month, a rates-sensitive headwind, although the figures are older than the current market snapshot (https://www.bls.gov/news.release/empsit.nr0.htm).
- October CPI and real earnings are scheduled for Tuesday, Nov. 10 at 08:30 ET, outside this overnight window but relevant to weekly risk (https://www.bls.gov/schedule/2026/11_sched_list.htm).
- Friday's Nasdaq rose 1.1% and semiconductors gained 4.2%, showing active dip-buying even as Nasdaq recorded a fourth consecutive weekly decline; this is the strongest contradiction to the bearish read (https://www.reuters.com/business/nasdaq-futures-rise-after-steep-ai-selloff-chip-stocks-stabilize-2026-11-06).
- The Nasdaq had entered correction territory during the Nov. 5 technology selloff, supporting structural vulnerability without proving further overnight downside (https://www.reuters.com/business/sp-500-futures-steady-after-midterm-rally-nasdaq-lags-chip-weakness-2026-11-05).
- Friday driver performance was mixed but squeeze-prone: NVDA gained 2.7753% and TSLA 4.2276%, while MSFT lost 0.9927% and AAPL lost 0.523%; quotes are from Nov. 6 and are supplemental, not directional overrides.
Sources & evidence dates · 24
- BLS confirms October CPI and real earnings are scheduled for Tuesday, November 10, 2026 at 08:30 ET, and October PPI for Friday, November 13 at 08:30 ET.2026-11-03
- bls.gov2026-11-06T08:30:00-05:00
- reuters.com2026-11-06
- Friday price action supplied a counter-signal to the bearish MNQ/MES thesis: Reuters reported the Nasdaq rose 1.1%, the S&P 500 rose 0.31%, and semiconductors rallied 4.2% on November 6. The Nasdaq nevertheless recorded a fourth consecutive weekly decline, so the rebound did not by itself repair the larger bearish structure.2026-11-06
- reuters.com2026-11-05
- The FRED page confirms DFII10 is the daily 10-year inflation-indexed Treasury yield series sourced from the Federal Reserve, but the fetched page did not expose the claimed 2.60% value for November 5. That number cannot be treated as current without a directly retrieved observation.
- Treasury's November TBAC report confirms two-year and ten-year yields had risen roughly 50 and 40 basis points since August, respectively, amid stronger activity, energy disruption and tighter policy expectations. It also says recent Treasury auctions remained generally resilient and found no persistent deterioration in auction demand, contradicting any implication that financing stress had already become an auction-demand crisis.2026-11-04
- treasurydirect.gov
- tradingview.com2026-11-06
- Yahoo2026-11-09T11:45:00.000Z
- Yahoo2026-11-09T11:40:52.000Z
- Yahoo2026-11-09T11:40:45.000Z
- Yahoo2026-11-09T11:06:48.000Z
- Yahoo2026-11-09T11:06:23.000Z
- Yahoo2026-11-09T11:06:04.000Z
- Yahoo2026-11-09T11:06:08.000Z
- Yahoo2026-11-09T11:30:24.000Z
- Yahoo2026-11-09T11:29:29.000Z
- Yahoo2026-11-09T11:37:30.000Z
- Yahoo2026-11-09T11:05:52.000Z
- Yahoo2026-11-09T11:49:00.000Z
- Yahoo2026-11-09T11:33:29.000Z
- Yahoo2026-11-09T11:30:24.000Z