The Lines in the Sand
The Trap
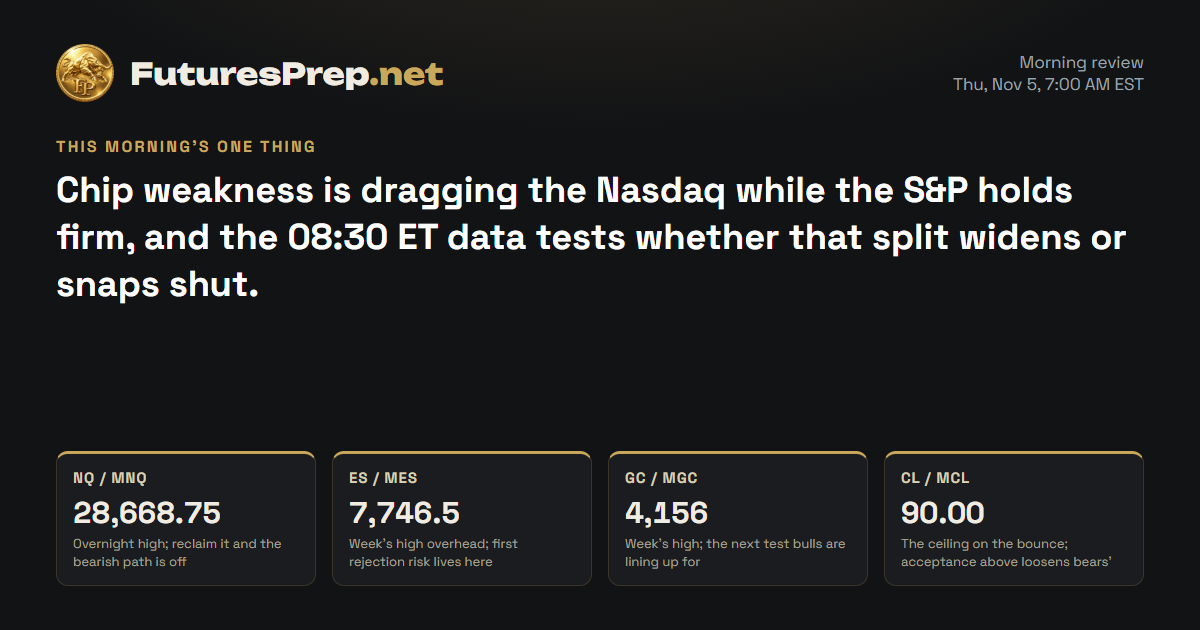
The overnight bounce looks like a recovery, and late chasers tend to run it straight into the 28465-28500 ceiling where the rally already stalled. The other side gets caught pressing the downside after a 501.75-point overnight range has already burned most of a normal day's move.
The Read
The bears drove price down to 27611.50, but they could not keep it there. The bulls dragged it back through the 28587 weekly open to close at 28646.25, so shorts from the breakdown below 28232.25 are now offside. Still, the bulls do not own the high ground: the close sits well under the daily EMA21 at 29476.39, and the weekly candle is a doji that shows nobody is in control. The tell is a split tape, with software and platform giants carrying the rebound while chipmakers lagged. Hold above 28500 and a retest of 28775-28900 opens, with 28970.75 the wall behind it. Lose 28500 and 28250 comes right back into play.
Morning review · Nov 5, 7:30 AM EST
Bulls clawed MNQ back from 28167 to 28444 overnight, but bears still own the bigger picture: price broke last week's low at 28232.25 and sits far beneath its daily average after a rejection there. The bounce is real but cramped under 28465-28500, and chip weakness is why the Nasdaq lags the S&P. Falling yields and a softer dollar give bulls a thin edge at best. Clear 28668.75 and the bearish path is off the table; lose 28389 and the floor toward 28232.25 is gone.
Overnight evidence · 11 cited findings
Overnight price action
- From the 18:30 ET baseline, MNQ produced a 28668.75 high, a 28167 low and a 28444 last price.
- The overnight net change was -219.75 points across 0.873 ADR.
- Price filled the 28646.25 reopening gap before selling through the evening path.
- The 28167 low materially undershot every carried evening expected-path point; the rebound later regained the H1 EMA.
Overnight events
- The Bank of England raised Bank Rate by 25 basis points to 4.00% in an 8-1 vote (https://www.bankofengland.co.uk/monetary-policy-summary-and-minutes/2026/november-2026).
- Verified premarket reporting showed Nasdaq-100 futures underperforming S&P 500 futures (https://www.reuters.com/business/sp-500-futures-steady-after-midterm-rally-nasdaq-lags-chip-weakness-2026-11-05).
- The 08:30 ET U.S. productivity and claims releases remained unresolved at the report cutoff.
What changed
- The evening bullish direction is invalidated by the overnight decline and renewed higher-time-frame bearish alignment.
- Nasdaq-specific semiconductor pressure supports bearish confidence.
- The H1 recovery, lower yields and weaker dollar are meaningful opposing evidence.
- The 08:30 ET data window increases two-way expansion risk without changing price action ownership of direction.
Index drivers
| Ticker | Approx. weight | Day move | Next earnings | Top headline |
|---|---|---|---|---|
| NVDA | 8.4% | −3.17% | Nov 17 · After close | Microsoft walks away from AI deal as $170 billion question grows |
| MSFT | 5.75% | +6.68% | — | Microsoft walks away from AI deal as $170 billion question grows |
| AAPL | 7.28% | +5.31% | — | Dow Jones Futures Rise As Techs Fall; Apple, Microsoft, Amazon Flash Buy Signals |
| AMZN | 4.04% | +6.12% | — | Massive market rotation raises question: Is the sell-AI trade here to stay? |
| META | 3.26% | +1.44% | — | Massive market rotation raises question: Is the sell-AI trade here to stay? |
| AVGO | 2.47% | −2% | — | iShares PHLX SOX Semiconductor (SOXX) Sells AMD and NVDA on Nov. 3 |
| GOOGL | 3% | +3.18% | — | DTE Energy announces strategic sale of its non-utility DTE Vantage business; reports third quarter accomplishments including advancing data center growth that delivers unprecedented customer affordability benefits and filing long-term generation plan |
| TSLA | 2.81% | −3.34% | — | America just voted against AI. That might be good. |
Nvidia, Broadcom and Tesla all closed lower in the prior session, with chips doing the damage. Microsoft, Apple, Amazon, Alphabet and Meta closed higher, so the heavyweights are split rather than broken. Nvidia reports earnings on November 17 after the close.
Market data as of Nov 5, 7:33 AM EST · Weights as of 2026-09-30
Evidence · 10 cited findings
Price action · weekly / daily / H1
- Weekly price accepted below 28232.25 but recovered from 27611.50 through the 28587 weekly open, leaving a developing rejection rather than clean downside continuation; 28970.75 remains resistance.
- The daily candle recovered bullishly across 2.37 ADR on 1.49 times 30-day average volume, but the 28646.25 close remains 1.44 ADR below the 29476.39 EMA21, so the advance is still corrective.
- H1 closed above its 28486.63 EMA21 and supports a retest of 28775-28900; movement below 28500 would expose 28250 and invalidate the immediate bullish path.
Metrics
- The completed daily range was 1359.25 points versus 574.82 ADR, confirming exceptional volatility and reducing confidence in a smooth continuation.
- The last completed H1 range was 84.5 points, below the 105-point expansion threshold, with one bar since the last expansion.
- The 17.5-point reopening gap at 28646.25 was already filled; the applicable historical bucket reports an 87.13% same-session fill rate from 101 observations.
- Large QQQ drivers were mixed: MSFT +6.68%, AAPL +5.31%, AMZN +6.12% and GOOGL +3.18% supported the rebound, while NVDA -3.17%, TSLA -3.34% and AVGO -2.00% limited confirmation (https://www.invesco.com/qqq-etf/en/about.html).
Sentiment & current events
- Preliminary Q3 productivity and costs are scheduled for November 5 at 08:30 ET, after this overnight projection and near the proposed next session (https://www.bls.gov/schedule/2026/11_sched_list.htm).
- The Bank of England announcement is scheduled for November 5 at 07:00 ET and may create cross-asset volatility before the U.S. data window (https://www.bankofengland.co.uk/monetary-policy/upcoming-mpc-dates).
- ADP reported an 86,000 October private-employment increase, but it is not a dependable one-for-one forecast of the November 6 BLS Employment Situation (https://adpemploymentreport.com/artifacts/us_ner/20261104/ADP_NATIONAL_EMPLOYMENT_REPORT_Press_Release_2026_10%20FINAL.pdf).
Sources & evidence dates · 21
- BLS confirms the next major U.S. releases are preliminary Q3 productivity and costs on November 5 at 08:30 ET, the October Employment Situation on November 6 at 08:30 ET, and October CPI and real earnings on November 10 at 08:30 ET.2026-11-03
- adpemploymentreport.com2026-11-04
- The Bank of England confirms a November 5 monetary-policy announcement at 12:00 GMT/07:00 ET. Bank Rate entered the meeting at 3.75%; the previous September decision was a 6-3 vote to hold, with three members preferring an increase.2026-09-17
- cmegroup.com
- Yahoo2026-11-05T11:53:13.000Z
- Yahoo2026-11-05T11:50:00.000Z
- Yahoo2026-11-05T11:35:00.000Z
- Yahoo2026-11-05T11:47:27.000Z
- Yahoo2026-11-05T11:34:37.000Z
- Yahoo2026-11-05T11:32:40.000Z
- Yahoo2026-11-05T11:13:28.000Z
- Yahoo2026-11-05T11:12:00.000Z
- Yahoo2026-11-05T11:26:02.000Z
- Yahoo2026-11-05T11:04:41.000Z
- Yahoo2026-11-05T11:03:56.000Z
- Yahoo2026-11-05T11:01:00.000Z
- Yahoo2026-11-05T11:55:00.000Z
- Yahoo2026-11-05T11:45:00.000Z
- Yahoo2026-11-05T12:00:00.000Z
- Yahoo2026-11-05T11:37:03.000Z
- Yahoo2026-11-05T11:11:23.000Z