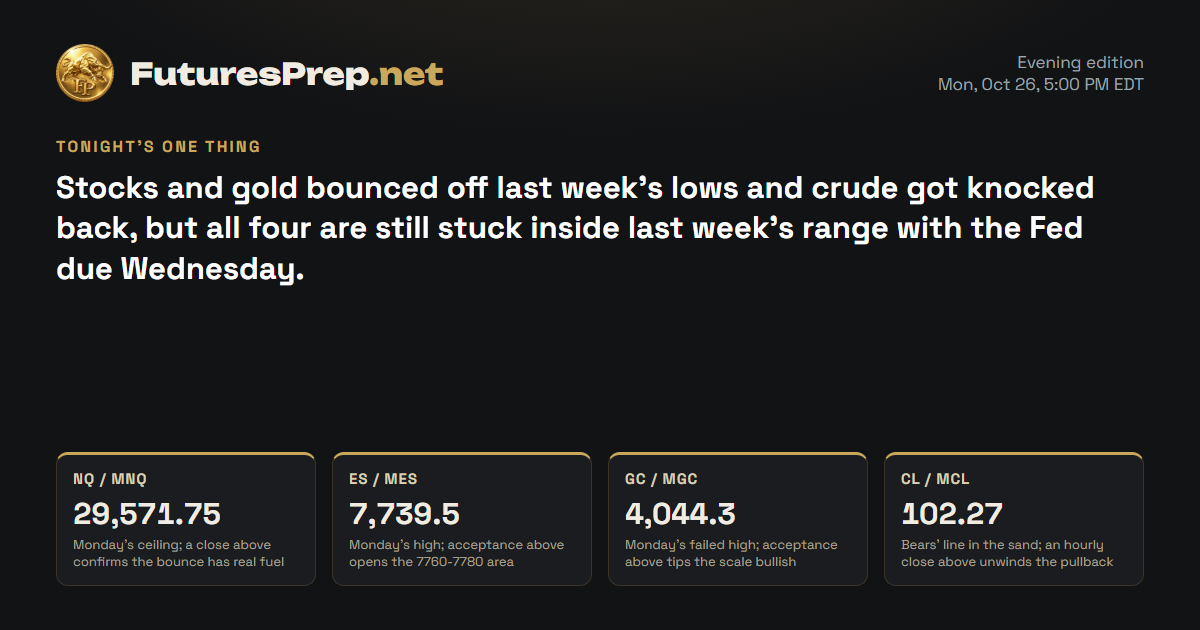
The Lines in the Sand
The Trap
After a big green day, late bulls tend to chase a quiet tape straight into 29571.75 and forget price is still well under the 30085.07 EMA21 that rejected it. When the hourly bars shrink like this, the next push often runs the late crowd before it picks a direction.
The Read
Bears had last week's low at 28986.25 in sight and lost the fight at 29024. Bulls drove price back to 29466.75 on heavier than usual volume, and the hourly chart is holding above its rising average. The tell is the stall: tight hourly bars just under 29571.75, and the daily close still sits far below the 30085.07 EMA21. That is a recovery, not a reversal, and the mixed tech heavyweights plus a Fed decision Wednesday give the bears a real counter-argument. Hold above 29571.75 and the door opens toward last week's 30114 high; lose 29397 and the bounce fades into rotation, with 29024 the floor that matters.
Index drivers
Tesla, Nvidia, Broadcom and Microsoft led the gains, and Amazon edged higher. Apple, Meta and Alphabet closed lower, so the support was uneven. Headlines flagged Microsoft, Amazon and Alphabet earnings as the big story this week.
Market data as of Oct 26, 6:33 PM EDT · Weights as of 2026-09-30
Evidence · 11 cited findings
Price action · weekly / daily / H1
- Weekly structure begins green after price defended 29024 near the 28986.25 prior-week low, but MNQ remains inside last week's range and has not accepted toward 30114.
- The daily candle rallied from 29024 to 29466.75 on 1.243 times its 30-day average volume, while the close remained 1.202 ADR below the rejecting 30085.07 EMA21; this is a recovery, not a confirmed daily reversal.
- H1 closed above its rising 29324.32 EMA following the 10:00 expansion and then consolidated beneath 29571.75; holding 29426 supports another test higher, while an H1 close below 29397 weakens the bullish path.
- The projected path is 29420 at 22:00, 29510 at 06:00, 29720 at 10:00 and 29640 at the 16:00 resolution close.
Metrics
- Monday used 1.064 ADR and closed bullish at 29466.75 after a 547.75-point range, demonstrating recovery demand but leaving much of the broader technical damage unrepaired.
- The last completed H1 range was only 43.5 points versus a 105-point expansion threshold, so the next projected impulse is conditional on a close above 29571.75.
- Major QQQ drivers were mixed: NVDA gained 2.3891%, MSFT 1.5424%, AVGO 2.3284% and TSLA 5.212%, while AAPL lost 1.0971%, META 1.8767% and GOOGL 1.0649%; weights are from Invesco and quotes are supplemental, not directional inputs (https://www.invesco.com/qqq-etf/en/about.html).
- Primary CME data sufficient to reproduce every supplied bar, EMA and ADR value were not retrieved, so the technical path remains a model-generated hypothesis (https://www.cmegroup.com/market-data/settlements.html).
Sentiment & current events
- Treasury's schedule supports 2-year, 5-year, FRN and 7-year supply this week, adding event risk, though exact auction times were not established from the reviewed source (https://fiscaldata.treasury.gov/datasets/upcoming-auctions/).
- The wider central-bank cluster includes BoC and RBNZ Wednesday, ECB Thursday and BoJ Friday; exact market probabilities remain time-sensitive secondary estimates (https://www.newsquawk.com/daily/5825-week-in-focus-26-30th-october-2026-highlights-include-fomc-boc-rbnz-ecb-boj-policy-decisions-us-pce).
- Sentiment evidence is mixed rather than unusually one-sided, and recent instrument-specific crowding could not be established from a defensible sample.
Sources & evidence dates · 26
- federalreserve.gov2025-06-24
- bea.gov2026-06-15
- fiscaldata.treasury.gov2026-10-23
- Reuters reported 28 confirmed or reported attacks in and around the Strait of Hormuz during October and 113 since the U.S.-Israeli war with Iran began. A syndicated Reuters copy says the tally broadly aligns with IMO data, but the underlying live incident database was not independently inspected.2026-10-23
- cmegroup.com
- Current discretionary commentary for MNQ, MES, MGC and MCL is mixed and conditional. TradingView and blog levels are observable published opinions, but their claimed liquidity, gamma, value-area and directional significance were not independently reproducible from primary CME data and cannot validate the price action forecasts.
- The global central-bank event cluster is supported by current schedules and previews: BoC and RBNZ decisions are due Wednesday, ECB Thursday and BoJ Friday. Exact market-implied probabilities and economist counts remain time-sensitive secondary estimates rather than primary-source facts.2026-10-23
- Yahoo2026-10-26T21:40:15.000Z
- Yahoo2026-10-26T21:36:02.000Z
- Yahoo2026-10-26T21:23:53.000Z
- Yahoo2026-10-26T21:47:27.000Z
- Yahoo2026-10-26T21:15:14.000Z
- Yahoo2026-10-26T21:00:02.000Z
- Yahoo2026-10-26T20:45:03.000Z
- Yahoo2026-10-26T20:07:19.000Z
- ChartMill2026-10-26T19:06:03.000Z
- Yahoo2026-10-26T21:14:15.000Z
- Yahoo2026-10-26T20:57:39.000Z
- Yahoo2026-10-26T21:03:50.000Z
- Yahoo2026-10-26T21:02:57.000Z
- Yahoo2026-10-26T20:54:47.000Z
- Yahoo2026-10-26T20:59:26.000Z
- Yahoo2026-10-26T20:15:00.000Z
- Yahoo2026-10-26T17:11:00.000Z
- Yahoo2026-10-26T20:53:16.000Z
- Yahoo2026-10-26T20:53:02.000Z