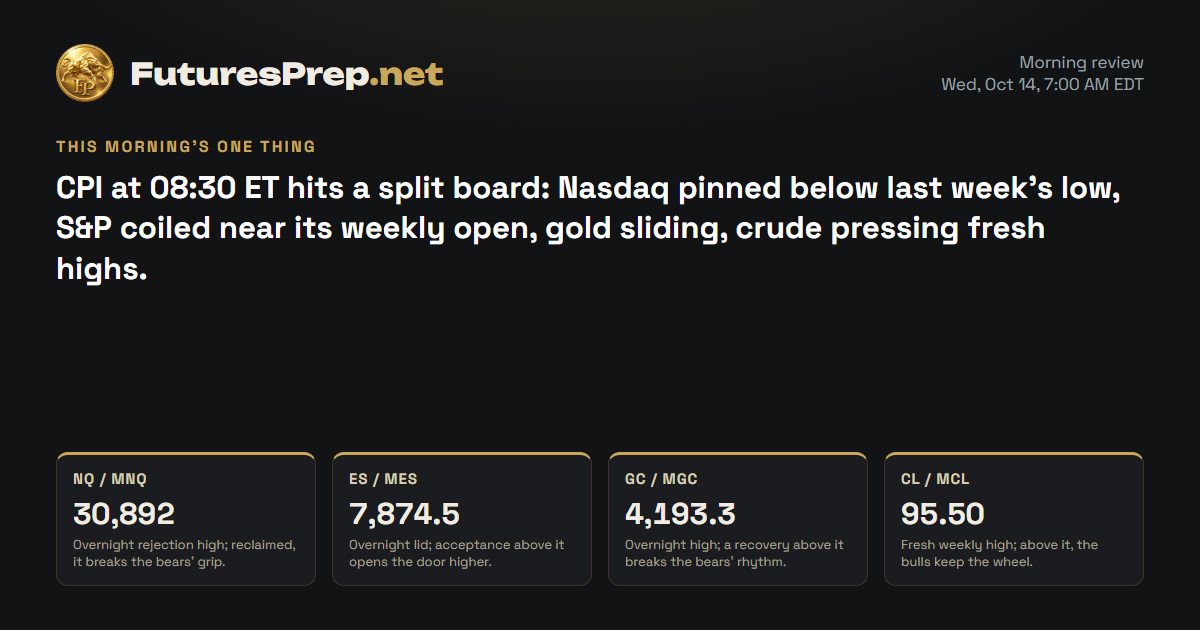
The Lines in the Sand
The Trap
Big tech closed green, and that tempts dip-chasers to fight a tape still stuck under last week's low. If a CPI spike fades back below 30792, the early longs are the ones left offside.
The Read
Bears took last week's floor at 30792, and the week closed under it at 30781.25. Bulls fought back hard off the 30591.25 flush, but the bounce died well short of 30905.5 and the day still closed red. The counter-argument is real: most Nasdaq heavyweights closed higher, and morning CPI can spark a relief rip. Below 30815 the trap door to 30690.5 and 30591.25 stays open; hourly closes back above 30905.5 put the bears offside.
Morning review · Oct 14, 7:31 AM EDT
Bears took last week's low at 30792 and kept price under it, but the tech heavyweights closed higher on October 13. That split is the fight. Price got rejected at 30891.5 overnight and slid back to 30757.25, still perched just above the daily EMA21 at 30726.08, so the bears have only a slight edge. Lose 30705.75 and the floor gives way; reclaim 30892 and the bearish case loses its grip.
Overnight evidence · 9 cited findings
Overnight price action
- From the evening baseline, MNQ traded from 30794.5 to 30891.5, then fell to 30705.75 and closed the 06:00 ET bar at 30757.25.
- The overnight net change was -37.25 points across a 185.75-point range, or 42.1% of ADR.
- Price crossed and closed through the prior 30792 thesis invalidation while remaining above the 30705.75 overnight low.
- The prior expected rebound toward 30820 occurred and was exceeded, but the projected 30685 level had not been reached by the observation cutoff.
Overnight events
- The CPI release remained pending at the 07:31 ET engine cutoff, and precise consensus estimates were not uniformly corroborated.
What changed
- Accepted weekly downside and the failed 30891.5 rebound preserve the evening bearish read.
- Gap completion removes the small 30781.25 gap as an unresolved objective.
- Remaining ADR capacity and H1 compression support expansion risk below 30705.75.
- Positive QQQ constituent breadth and CPI event risk reduce confidence but do not alter direction.
Index drivers
NVDA, MSFT, AAPL, META, AVGO and GOOGL all closed higher on October 13, with META posting the biggest gain of the group, while AMZN and TSLA finished lower. Earnings start landing next week: TSLA on October 20 and META on October 21, both after the close, then GOOGL on October 27 after the close and MSFT on October 28.
Market data as of Oct 14, 7:35 AM EDT · Weights as of 2026-09-30
Evidence · 9 cited findings
Price action · weekly / daily / H1
- Weekly price accepted below the prior-week low at 30792 and closed at 30781.25, 363.25 points below the 31144.5 weekly open; that acceptance owns the bearish direction.
- The daily candle recovered from 30591.25 but still closed bearish at 30781.25; it held 55.17 points above the 30726.08 daily EMA21 while failing to recover 30905.5.
- H1 stabilized around its EMA21 after the selloff, creating bounce risk, but failure below 30815 leaves 30690.5 and 30591.25 exposed; sustained closes above 30905.5 invalidate the immediate bearish scenario.
Metrics
- The completed daily range was 314.25 points, 71.3% of the 441.03-point ADR, leaving room for another directional session without requiring an exceptional range.
- Daily volume was 1.497 times its 30-session average, strengthening the significance of the bearish close and failed recovery.
- The last H1 range was only 43.5 points versus a 105-point expansion threshold, so compression precedes the projected 09:00-11:00 ET next session.
Sentiment & current events
- September CPI and Real Earnings are scheduled for 08:30 ET on October 14, making the bearish path vulnerable to a relief reaction; the official schedule is verified, while consensus and reaction thresholds remain nonofficial forecasts: https://www.bls.gov/schedule/2026/10_sched.htm
- Large QQQ drivers were mixed-to-positive after the close: NVDA gained 0.9721%, MSFT 0.425%, AAPL 0.088%, META 2.63% and AVGO 0.7273%, while AMZN lost 0.366% and TSLA lost 0.7407%; this breadth is the strongest contradiction to the bearish futures structure: https://www.invesco.com/qqq-etf/en/about.html
- Unresolved Iran-US negotiations over reopening the Strait of Hormuz preserve cross-asset headline risk but do not independently establish the next MNQ direction: https://www.reuters.com/world/middle-east/iran-says-strait-hormuz-will-not-reopen-until-conditions-are-met-2026-10-04
Sources & evidence dates · 31
- BLS confirms September 2026 CPI and Real Earnings are scheduled for October 14, 2026 at 08:30 ET; September PPI is scheduled for October 15 at 08:30 ET and Import/Export Prices for October 16 at 08:30 ET.2026-02-18
- Multiple current previews report expectations near +0.6% m/m and +3.6% y/y for headline CPI and +0.2% m/m and +2.5% y/y for core CPI. These are forecasts, not official BLS figures; other forecast sources show modestly different consensus estimates.2026-10-13
- bls.gov2026-02-18
- The Federal Reserve calendar confirms Vice Chair for Supervision Bowman appearances at 05:40 ET and 22:55 ET on October 14, the Beige Book at 14:00 ET on October 14, and Chairman Kevin Warsh's IMF conversation at 23:30 ET on October 15.2025-06-24
- reuters.com2026-10-04
- reuters.com2026-10-06
- cmegroup.com
- riotimesonline.com2026-10-13
- Yahoo2026-10-14T09:39:00.000Z
- Yahoo2026-10-14T09:35:00.000Z
- Yahoo2026-10-14T09:32:02.000Z
- Yahoo2026-10-14T10:28:03.000Z
- Yahoo2026-10-14T09:54:55.000Z
- Yahoo2026-10-14T09:00:00.000Z
- Yahoo2026-10-14T08:38:53.000Z
- Yahoo2026-10-14T08:35:00.000Z
- Yahoo2026-10-14T08:20:50.000Z
- Yahoo2026-10-14T09:08:02.000Z
- SeekingAlpha2026-10-14T03:20:00.000Z
- Yahoo2026-10-13T23:30:06.000Z
- Yahoo2026-10-14T09:00:00.000Z
- Yahoo2026-10-14T08:58:47.000Z
- Yahoo2026-10-14T09:27:00.000Z
- SeekingAlpha2026-10-14T06:05:00.000Z
- Yahoo2026-10-14T05:12:36.000Z
- Yahoo2026-10-14T09:26:01.000Z
- SeekingAlpha2026-10-14T06:12:40.000Z
- Yahoo2026-10-14T05:24:49.000Z
- Yahoo2026-10-14T09:11:15.000Z
- Yahoo2026-10-14T08:51:40.000Z
- Yahoo2026-10-14T06:39:09.000Z