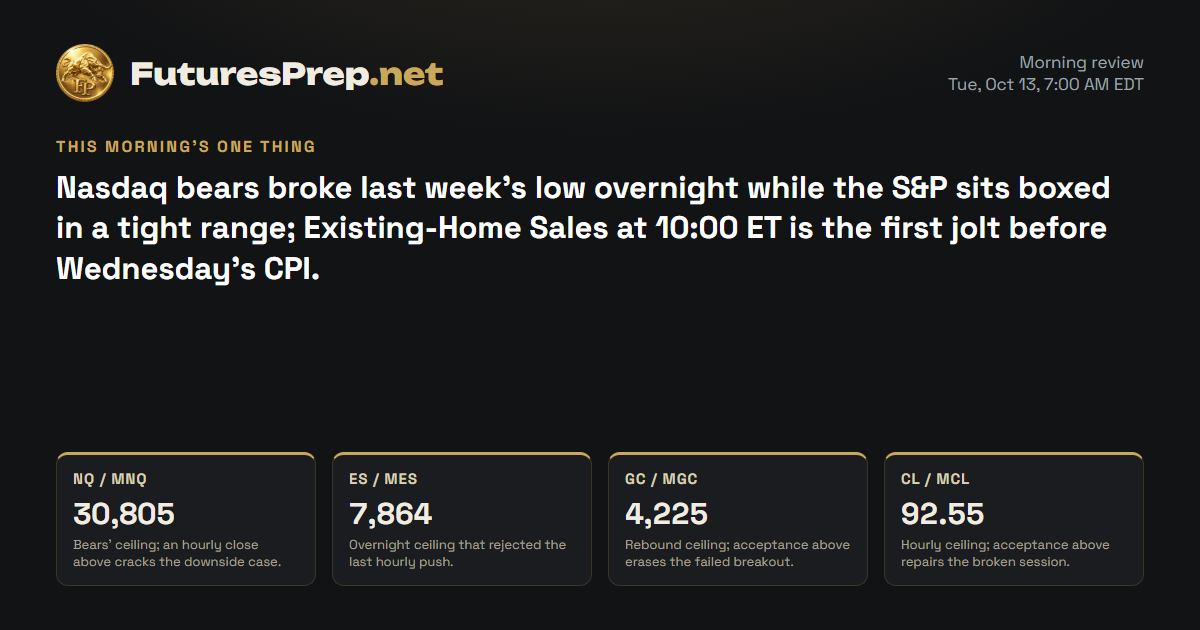
The Lines in the Sand
The Trap
The tell is the sweep: price ran through last week's low at 30792 but has not settled below it. Traders who press late into that flush tend to get caught when falling yields lift tech back toward 30805.
The Read
Bulls made a run at 31290 and got thrown back hard. Price sliced under the 31123.25 prior-week close and settled at 30877.5, barely off the 30842.5 low, on heavier-than-usual volume. Bears have the edge, but bulls still have ground under them: the untouched 30792 prior-week low and the 21-day average at 30717.42 sit right below, and the megacaps were split rather than stampeding. Lose 30842.5 and the path to 30792 opens; a completed hourly close back above 31010 and the bears are the ones offside.
Morning review · Oct 13, 7:30 AM EDT
Bears drove price through last week's low at 30792 overnight and tagged 30606.75, but bulls dragged it back to 30720.75, right on the daily average at 30717.42. The hourly chart still sits under a falling average, and the bounce has looked tired. The strongest counter is the bond market: Treasury yields fell this morning, a cushion for tech. Lose 30606.75 and the floor is gone; reclaim 30805 with acceptance and the bears are offside.
Overnight evidence · 13 cited findings
Overnight price action
- From the prior-evening baseline, MNQ traded from a 30905.5 overnight high to 30606.75 and was 156.75 points lower at 30720.75.
- Price crossed the 30792 weekly-thesis invalidation and completed H1 closes below it, but the engine has not recorded accepted weekly trade below the level.
- The rebound from 30606.75 reached 30774.25 before the latest completed hour closed at 30720.75 below its 30801.02 H1 EMA21.
- The overnight range used 0.68 ADR and did not produce a qualifying 105-point expansion in the latest hour.
Overnight events
- No verified event reaction cleanly explains the overnight decline.
- Falling Treasury yields provide a tactical bullish counterforce rather than confirmation of the decline. Source: https://www.cnbc.com/2026/10/13/us-treasurys-bonds-yields.html
- The RBA minutes occurred before the cutoff and are not a forward catalyst. Source: https://www.rba.gov.au/coming-up/
- The 10:00 ET housing release remains the principal verified event inside the remaining session window. Source: https://www.nar.realtor/research-and-statistics/housing-statistics/existing-home-sales
What changed
- Price action preserves the prior bearish read and retains sole directional authority.
- Overnight downside and weekly invalidation stress support bearish confidence.
- Failure to accept below 30792 and the rebound from 30606.75 warn against treating continuation as confirmed.
- Falling yields and mixed megacap leadership reduce confidence.
- The MORNING verdict is unchanged because the prior bearish structure remains intact beneath 30805.
Index drivers
| Ticker | Approx. weight | Day move | Next earnings | Top headline |
|---|---|---|---|---|
| NVDA | 8.4% | −1.29% | — | Stock Market Today: Micron, Sandisk Fall on China Memory News |
| MSFT | 5.75% | +1.14% | — | Stock Market Today: Micron, Sandisk Fall on China Memory News |
| AAPL | 7.28% | +1.29% | — | South Korea Exchange Ban Hits KuCoin, MEXC and 25 Other Platforms |
| AMZN | 4.04% | −1.11% | — | Generac Entered a Massive Deal With Amazon. Is It Time to Buy the Stock? |
| META | 3.26% | +3.38% | — | Stock Market Today: Micron, Sandisk Fall on China Memory News |
| AVGO | 2.47% | −1.88% | — | Stock Market Today: Micron, Sandisk Fall on China Memory News |
| GOOGL | 3% | +0.3% | Oct 27 · After close | South Korea Exchange Ban Hits KuCoin, MEXC and 25 Other Platforms |
| TSLA | 2.81% | −1.22% | Oct 20 · After close | Cybertruck Deliveries Look Dismal Again, After Truck Called “Biggest Flop In Automotive History” |
Monday's heavyweights were split: Nvidia, Amazon, Broadcom and Tesla closed lower, while Apple, Microsoft and Meta finished higher, with Meta posting the biggest gain. This morning's chip headlines point to a deepening global chip selloff on AI worries and China competition. Tesla reports October 20 and Alphabet October 27, both after the close.
Market data as of Oct 13, 7:34 AM EDT · Weights as of 2026-09-30
Evidence · 9 cited findings
Price action · weekly / daily / H1
- Weekly structure opened below the 31123.25 prior close, rejected 31290 and settled near the 30842.5 session low; the untaken 30792 prior-week low is the nearest downside liquidity.
- The 447.5-point bearish daily range used 1.018 ADR on 1.265 times 30-day average volume, while the close remained above the 30717.42 daily EMA21; continuation pressure therefore meets meaningful support at 30792-30717.
- H1 produced lower highs and lower lows and finished below its 31009.67 H1 EMA21; a close below 30842.5 activates the downside expansion case, while acceptance above 31010 weakens it.
Metrics
- The bearish session consumed slightly more than one ADR and closed only 35 points above its low, supporting downside control without proving acceptance below weekly support.
- Large-cap technology drivers were mixed: NVDA fell 1.291%, AMZN 1.1051%, AVGO 1.8836% and TSLA 1.2203%, while AAPL rose 1.2862%, MSFT 1.1363% and META 3.3799%; this limits confirmation from the index leadership snapshot. Source: https://www.invesco.com/qqq-etf/en/about.html
- The last completed H1 range was only 29.25 points versus a 105-point expansion threshold, so the late compression requires a fresh range break rather than implying that expansion is already underway.
Sentiment & current events
- Fresh secondary commentary described subdued U.S. equity futures ahead of earnings and inflation data, which is consistent with caution but does not independently establish downside continuation. Source: https://www.kitco.com/news/off-the-wire/2026-10-12/us-stock-futures-steady-oil-jumps-two-week-high-ahead-key-earnings
- The September CPI release is scheduled for 2026-10-14 at 08:30 ET and the Beige Book for 14:00 ET; neither event falls inside this 12-hour forecast, and their outcomes are unknown. Sources: https://www.bls.gov/schedule/news_release/cpi.htm and https://www.federalreserve.gov/newsevents/2026-october.htm
- The Columbus Day fixed-income closure and Tuesday release of delayed Federal Reserve statistics can increase repricing risk, but no verified directional outcome is available. Sources: https://www.sifma.org/news/press-releases/sifma-fixed-income-market-close-recommendations-in-the-u-s-the-u-k-and-japan-for-u-s-columbus-day-and-japan-health-and-sports-day-holidays-2026 and https://www.federalreserve.gov/newsevents/2026-october.htm
Sources & evidence dates · 29
- bls.gov
- The Federal Reserve schedules the Beige Book for Wednesday, 2026-10-14 at 14:00 ET. Its contents and resulting yield or asset-price reactions cannot be known before publication.
- sifma.org2026-09-29T00:00:00-04:00
- The Federal Reserve calendar states that daily and weekly statistical releases normally scheduled for Columbus Day will be released Tuesday, 2026-10-13.
- bls.gov
- tradingeconomics.com2026-10-09T00:00:00Z
- thenationalnews.com2026-10-09T00:00:00-04:00
- kitco.com2026-10-12
- cftc.gov2026-10-09
- Reddit evidence was stale or absent and is inactive S4 material; it provides no permissible directional evidence for any covered contract.
- ChartMill2026-10-13T10:24:10.000Z
- Yahoo2026-10-13T09:42:00.000Z
- Yahoo2026-10-13T09:30:00.000Z
- Yahoo2026-10-13T10:00:00.000Z
- Yahoo2026-10-13T09:00:07.000Z
- Yahoo2026-10-13T09:01:59.000Z
- Yahoo2026-10-13T08:35:15.000Z
- Yahoo2026-10-13T06:15:51.000Z
- Yahoo2026-10-13T09:19:00.000Z
- Yahoo2026-10-13T08:00:00.000Z
- SeekingAlpha2026-10-13T06:30:00.000Z
- Yahoo2026-10-13T09:27:41.000Z
- Yahoo2026-10-13T09:00:46.000Z
- Yahoo2026-10-13T08:56:57.000Z
- Yahoo2026-10-13T08:15:41.000Z
- Yahoo2026-10-13T05:20:28.000Z
- Yahoo2026-10-13T09:42:48.000Z
- Yahoo2026-10-13T09:05:00.000Z
- Yahoo2026-10-13T08:59:07.000Z